
Self-Employed Tax Calculator
See your Income Tax and National Insurance for 2026/27 in seconds, then keep the records that make the number right at Self Assessment.
Enter your annual profit, choose whether you live in Scotland or the rest of the UK, and this sole trader tax calculator shows your Income Tax, Class 4 National Insurance, and take-home for the 2026/27 tax year. Your bill starts from profit, so the expenses you record are what lower it.
Your self-employed profit for the year: sales minus allowable business expenses. Assumes this is your only taxable income.
Scotland sets its own Income Tax bands. National Insurance is the same across the whole UK.
Enter your annual profit to see your Income Tax and National Insurance for 2026/27.
Estimates only, for the 2026/27 tax year, assuming self-employment is your only taxable income and you take the standard Personal Allowance. It does not cover the High Income Child Benefit Charge, student loan repayments, pension relief, or Payments on Account. Check your figures with HMRC or an accountant.
Key takeaways
Two taxes on one profit
As a sole trader you pay Income Tax and Class 4 National Insurance on the same figure: your profit after allowable expenses. Class 2 National Insurance is no longer charged once profit reaches £7,105, but you still build up your State Pension record.
Your allowances come first
The first £12,570 of profit is covered by the Personal Allowance and taxed at 0%. Class 4 National Insurance also starts at £12,570. Above £100,000 the Personal Allowance tapers away, which is why the effective rate climbs.
Scotland is different
Scotland sets its own Income Tax bands, from a 19% starter rate to a 48% top rate. National Insurance is the same across the whole UK. Pick your nation in the calculator so the bands match.
Expenses decide the bill
Every allowable expense you record lowers the profit both taxes are charged on. A missed receipt is profit you pay tax on that you did not need to. This is the case for tracking expenses as they happen, not the week before the deadline.
Catch every expense so your profit is right
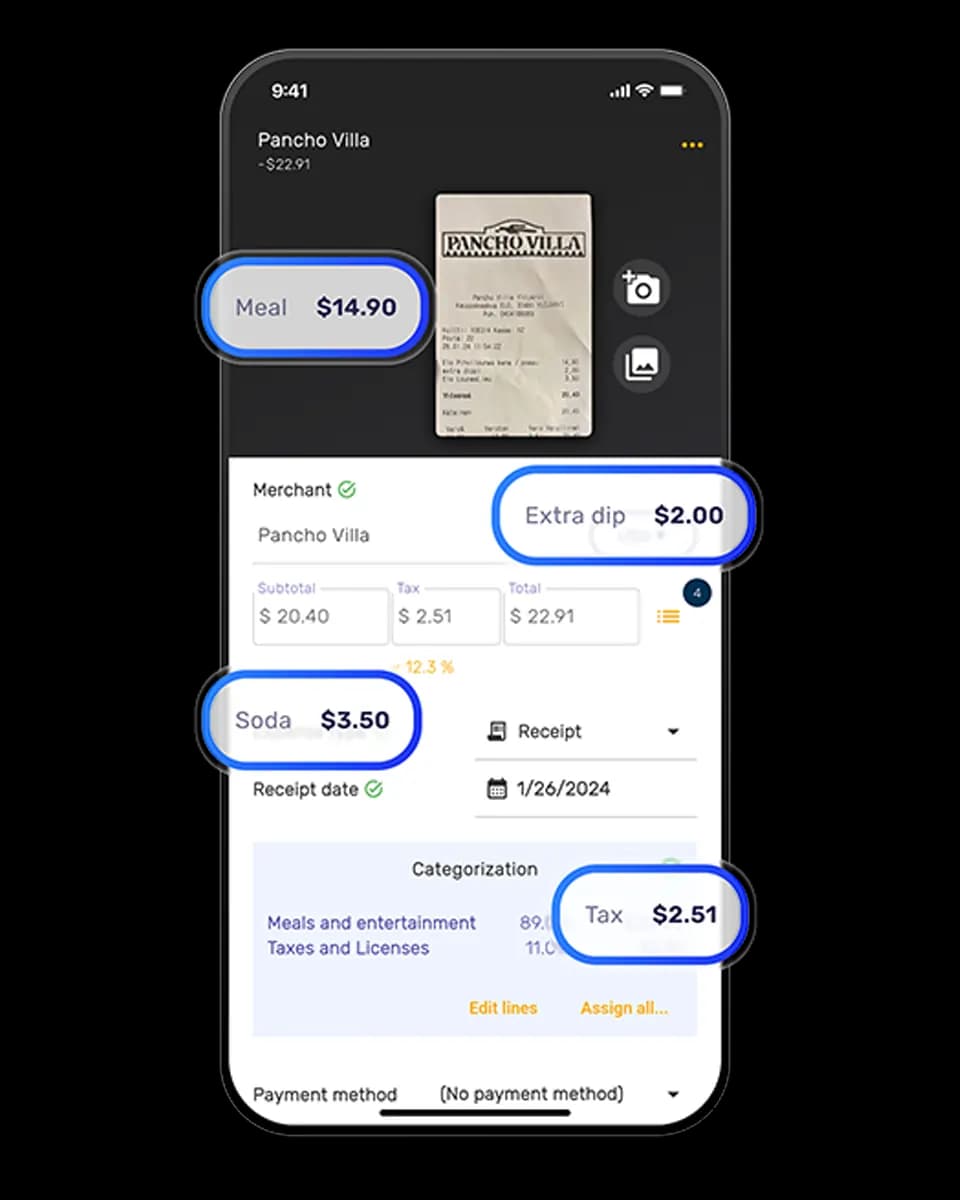
The number above is only as good as the expenses behind it. Snap a receipt at the till and SparkReceipt reads the merchant, date, total, and VAT in seconds, then sorts it into a category. Forward an email receipt or import a bank statement and the same thing happens. Nothing is left in a drawer to be typed up later, so the profit you file is the real one. On iPhone, Android, and the web.
Self Assessment figures ready when you are
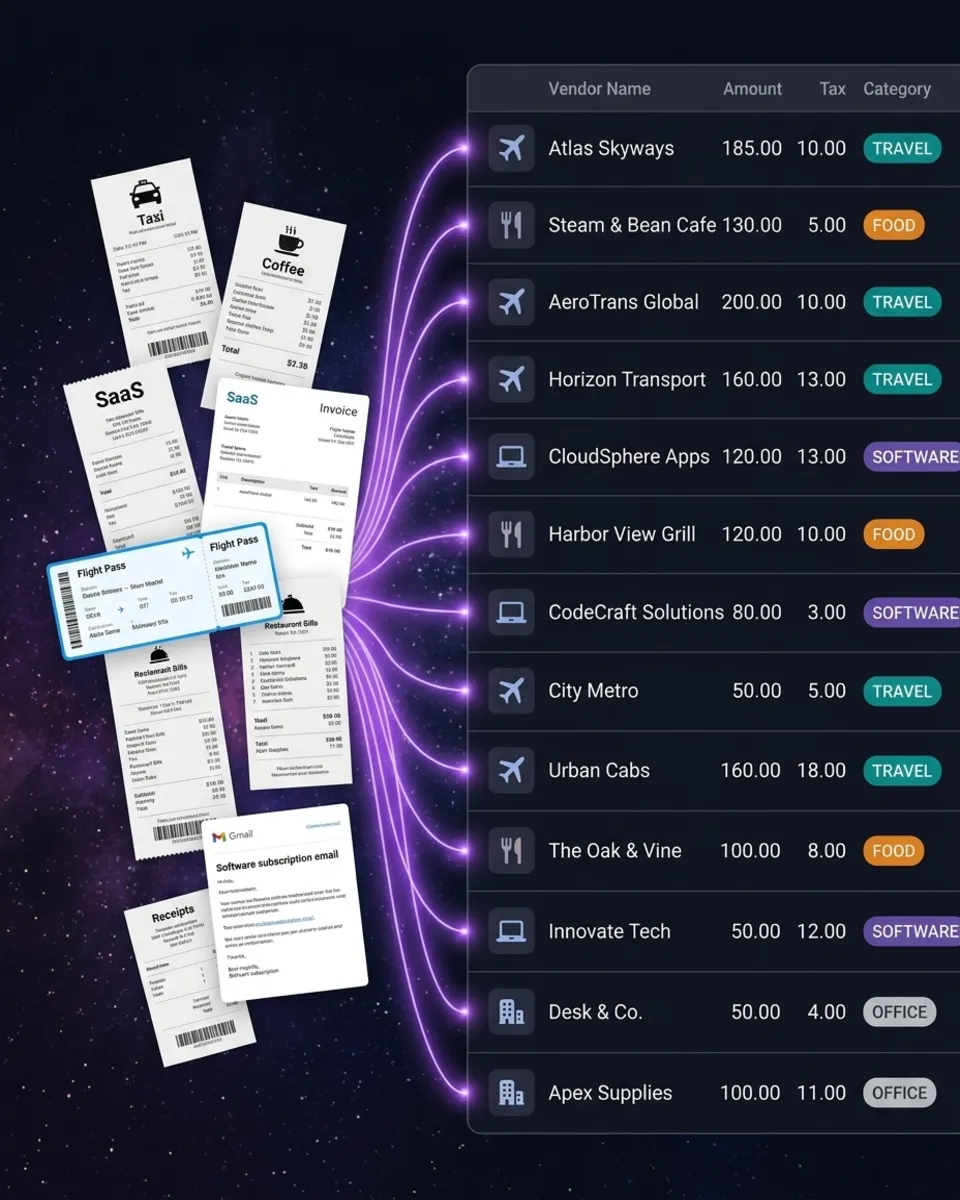
Come January, your income and expenses are already categorised and totalled, so working out profit is a matter of reading it off, not rebuilding a year of spending. Export the figures to a spreadsheet, or invite your accountant into the same account for free to file for you. Either way the records sit behind the return if HMRC ever asks.
How self-employed tax works in the UK
If you work for yourself as a sole trader, you pay tax on your profit: your income minus your allowable business expenses. Two charges come out of that profit for 2026/27:
- Income Tax. The first £12,570 is covered by the Personal Allowance and taxed at 0%. In England, Wales, and Northern Ireland the rest is taxed at 20% up to £50,270, 40% up to £125,140, and 45% above that. Scotland has its own bands, from a 19% starter rate to a 48% top rate.
- Class 4 National Insurance. Charged at 6% on profit between £12,570 and £50,270, and 2% on profit above £50,270. This is on top of Income Tax.
Class 2 National Insurance used to be a flat weekly charge. From 2024 it is no longer payable once your profit reaches the small profits threshold of £7,105: you keep your State Pension and benefit record without paying it. Below that threshold you can pay it voluntarily to protect your record.
There is also a trading allowance: if your self-employed income for the year is £1,000 or less, you usually do not need to report it or pay tax on it.
What counts as an allowable expense
Your tax bill starts from profit, so every allowable expense lowers it. Common ones for the self-employed include:
- Stock, materials, and the direct cost of what you sell
- Tools, software, and subscriptions used for the business
- Travel and mileage for business journeys (not your regular commute)
- A share of your home costs if you work from home
- Phone, broadband, and postage used for work
- Accountancy, insurance, and bank charges for the business
Keep the receipt behind each one. HMRC can ask you to show the records for a business expense, so a total in a spreadsheet with nothing behind it is a figure at risk. The expense tracker keeps the image attached to every line.
When you pay: the Self Assessment deadlines
The tax year runs from 6 April to 5 April. If you are newly self-employed, you register for Self Assessment by 5 October after the end of your first tax year. After that:
- 31 October is the deadline for a paper return.
- 31 January is the deadline for the online return and for paying the tax you owe.
If your Self Assessment bill is more than £1,000, HMRC also asks for Payments on Account: two advance payments towards next year's bill, due on 31 January and 31 July. The calculator above shows the tax and National Insurance on your profit; Payments on Account are a timing matter on top of that, so budget for them if this is your first bigger year.
Cut the January scramble
The tax itself is fixed by your profit and the bands. What you control is how much of the year you spend reconstructing it. Recording income and expenses as they happen, with the receipt attached, turns the return into reading off a total rather than a weekend of sorting through statements. If you would rather hand it over, your accountant works in the same account for free.
Frequently Asked Questions
As a sole trader you pay Income Tax and Class 4 National Insurance on your profit (income after allowable expenses). For 2026/27 the first £12,570 is tax-free under the Personal Allowance. In England, Wales, and Northern Ireland, profit above that is taxed at 20% to £50,270, 40% to £125,140, and 45% above. Class 4 National Insurance is 6% on profit from £12,570 to £50,270 and 2% above. Enter your profit in the calculator to see your own figure.
Class 4 National Insurance is charged on your profit: 6% on the part between £12,570 and £50,270, and 2% on anything above £50,270. Class 2 National Insurance is no longer payable once your profit reaches £7,105, though you keep your State Pension record. Below that you can pay Class 2 voluntarily.
Scotland sets its own Income Tax bands, which for 2026/27 run from a 19% starter rate up to a 48% top rate, so a Scottish sole trader can owe a different amount of Income Tax on the same profit. National Insurance is the same across the whole UK. Choose Scotland in the calculator to use the Scottish bands.
You can deduct allowable business expenses: stock and materials, tools and software, business travel and mileage, a share of home-working costs, business phone and broadband, and professional fees like accountancy and insurance. Each expense lowers the profit your tax is charged on, so keeping the receipts is what protects the deduction.
The online Self Assessment return and the tax payment are both due by 31 January after the end of the tax year. If your bill is over £1,000, HMRC also asks for Payments on Account: two advance instalments due on 31 January and 31 July. Newly self-employed people register for Self Assessment by 5 October after their first tax year.
It uses the published 2026/27 Personal Allowance, Income Tax bands (for both Scotland and the rest of the UK), and Class 4 National Insurance rates, and assumes self-employment is your only taxable income. It does not cover student loan repayments, the High Income Child Benefit Charge, pension relief, or Payments on Account, so treat it as an estimate and confirm your figures with HMRC or an accountant.
More tools and guides
Mileage Allowance Calculator
Work out your HMRC simplified mileage deduction
Home Office Calculator
The simplified working-from-home flat rate by hours
Expense Report Template
Free Excel and Google Sheets template, with an example
Receipt Scanner
Scan any receipt with AI in seconds
Bank Statement Extractor
Turn a PDF statement into categorised transactions
For Accountants
Invite your accountant into your account for free